FMA: mean KiwiSaver balance hits $40,340 as fees and hardship rise
The Financial Markets Authority says the mean KiwiSaver balance crossed $40,000 for the first time in the year to 31 March 2026, reaching $40,340 as funds under management climbed to $138.8 billion.
Regulation and Markets Conduct Reporter · 10/09/2026 · 10:46 NZT · 5 min read
"If your provider isn't delivering, you can move, and hundreds of thousands of Kiwis did exactly that."Cameron Brewer, Commerce and Consumer Affairs Minister
Auckland’s potential $5 billion Fast-track infrastructure exposure and 16,270 wrongly suspended Winter Energy Payments have become the first real-world stress tests of the Regulatory Standards Act 2025.
Cabinet’s Economic Policy Committee has formally authorised public consultation on a prudential levy to shift Reserve Bank supervision costs onto banks, insurers and market infrastructure operators from 2027/28.
Cabinet has agreed in principle to three shifts in public performance reporting sought by the Finance and Expenditure Committee, while parking detailed design and costings until 2027.
The Financial Markets Authority's KiwiSaver Annual Report for the year to 31 March 2026 puts the mean member balance at $40,340. That is an 11% rise from $36,349 a year earlier and the first time the average has cleared $40,000.
Membership stood at about 3.4 million. Total funds under management reached $138.8 billion. That pool is more than double the $62 billion the FMA recorded for the year to 31 March 2020.
Contributions hit a record $13.2 billion, up 8.2%. Net investment returns added $10.7 billion, well above the $6.4 billion booked in the prior year. More than 112,000 new members joined.
FMA head of investment management Emelie Jensert cast the milestone as a two-way duty. Providers need sound governance and clear disclosure. Members need to engage on contribution rates, fund choice and fees.
Commerce and Consumer Affairs Minister Cameron Brewer welcomed the growth and stressed competition. He pointed to elevated switching as evidence that members can exit underperforming providers.
"Competition is a key focus for this Government, and this report shows it working. Members switched funds 460,000 times last year and $7.4 billion moved between providers, up from $5.5 billion. If your provider isn't delivering, you can move, and hundreds of thousands of Kiwis did exactly that."
Growth alongside friction
The same report documents strains beside the headline average. Some 1.4 million members were not contributing regularly. Jensert said that group spans under-18s, retirees, parents on leave and people outside paid work. It does not simply show people who have quit saving by choice.
Total withdrawals were $6.8 billion. Age-65-and-over withdrawals rose 10.5% to $3.3 billion — nearly half of all withdrawals. The FMA said full withdrawals continue to fall, implying more retirees leave money invested rather than cash out entirely.
Hardship withdrawals jumped 19.8% to $531.5 million. That rise signals ongoing household stress even as aggregate balances climb. First-home withdrawals set a record: more than 50,000 people took out a combined $2.2 billion.
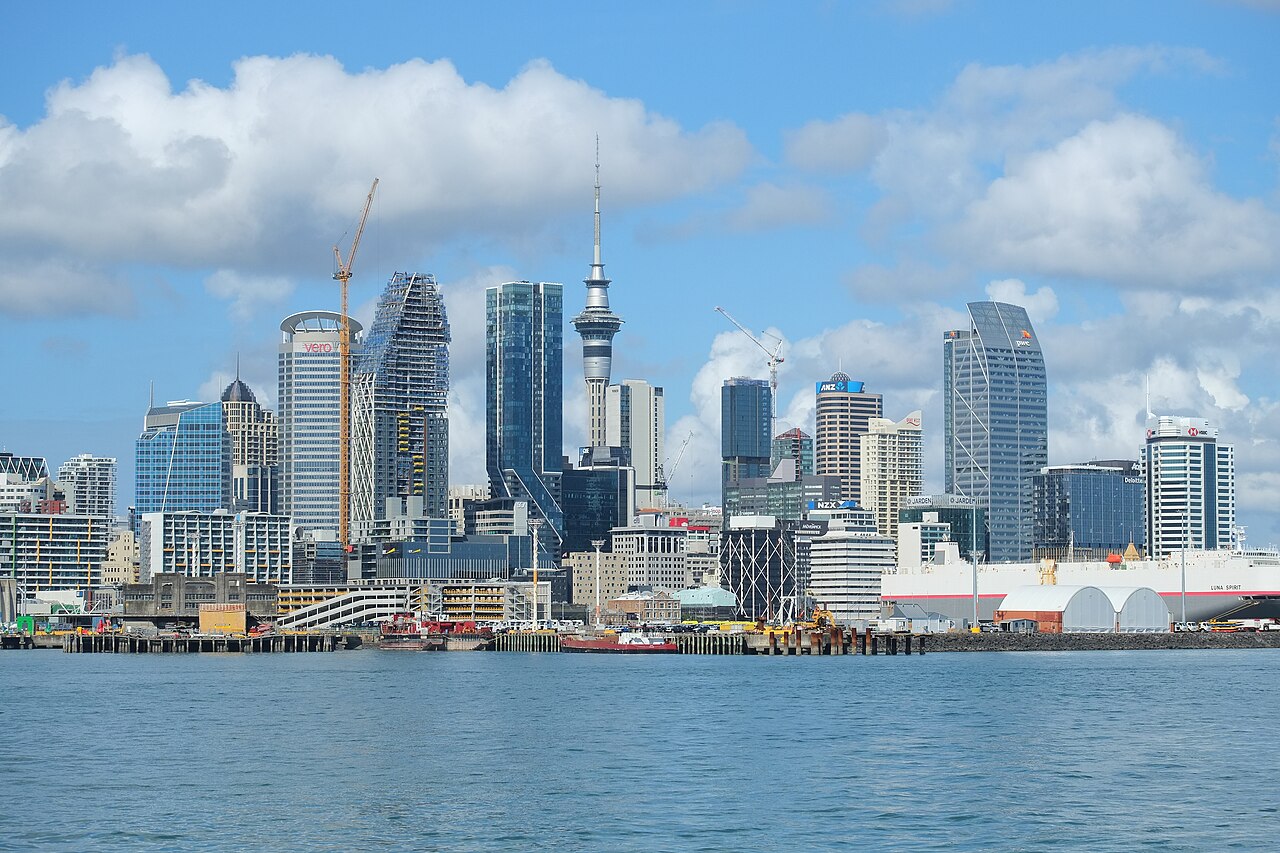
Auckland's financial district houses many of the banks and fund managers overseeing New Zealand's $138.8 billion KiwiSaver pool.
Fees, switching and fund flows
Members paid $978.2 million in fees, up 12.6% in dollar terms from $868.5 million the year before. Jensert said fees as a share of system funds under management have been flat for three years. The FMA will research provider fee trends in the year ahead and then consider next steps.
Absolute fee take often rises with assets even when basis-point pricing is stable. That scale dynamic keeps pressure on disclosure as balances grow.
Switching was elevated. Members switched funds 460,000 times. Transfers between providers totalled $7.4 billion, up from $5.5 billion. Growth funds drew the most switchers by count. Cash and conservative funds took the largest net inflows by value. Balanced and growth funds saw net outflows — a near-term cash preference worth watching.
Brewer urged members to check their fund, their fees and their provider.
"Check what fund you're in, check what you're paying, and don't be afraid to shop around. This Government's job is to keep that market competitive and well regulated so Kiwis have real choices."
Mean KiwiSaver balance, 2020-2026
The mean balance has roughly doubled over six years, driven by contributions, employer matching and mostly positive markets.
Source: FMA KiwiSaver Annual Reports 2020-2026
Distribution still matters more than the mean
A separate Te Ara Ahunga Ora Retirement Commission and Melville Jessup Weaver cut as at 31 December 2025 put the mean balance at $41,286. Men averaged $47,452 and women $38,212 — a persistent gap of about 24%. Contributing members averaged $50,727 versus $19,553 for non-contributors. The FMA March-year and Retirement Commission December figures are not directly interchangeable; different dates and bases apply.
About a third of members still held less than $10,000 at December 2025. About 15%, or roughly 450,000 members, held more than $80,000. At ages 61–65 the average was only around $78,000 — well short of common comfortable-retirement lump-sum benchmarks.
Policy settings and the year ahead
From 1 April 2026 the default employee and matching employer contribution rate rose from 3% to 3.5%, with a further step to 4% scheduled for 1 April 2028. Inland Revenue administers the change. Finance Minister Nicola Willis said in June 2026 that about 99.5% of regular employee contributors stayed on the higher default. Only about 9,300 of roughly 1.8 million opted out.
That rate lift sits only partly inside the March 2026 statistical year. The fuller contribution effect should show more clearly in the 2027 FMA report.
The Government has also advanced the KiwiSaver (First Home or Farm) Amendment Bill. It would widen first-home access for service-tenancy workers and farm purchases via commercial vehicles, consistent with the record first-home withdrawal print.
For markets conduct, the FMA's planned fee-trend work sits beside its 2026 Financial Conduct Report priority on KiwiSaver fees as balances and contribution settings rise. Competition metrics support the shop-around message. Absolute fee dollars still climbed faster than the average balance, so members who never review costs risk subsidising scale without clear value.
Jensert's three practical checks remain the member-facing bottom line:
Whether you are contributing, and at what rate
Whether you sit in the right fund for your life stage
Whether you understand the fees and whether the provider still fits
With a $139 billion household pool now on the books, those decisions compound for New Zealand households and for the managers who earn the $978 million fee line.