Under construction and near-term starts
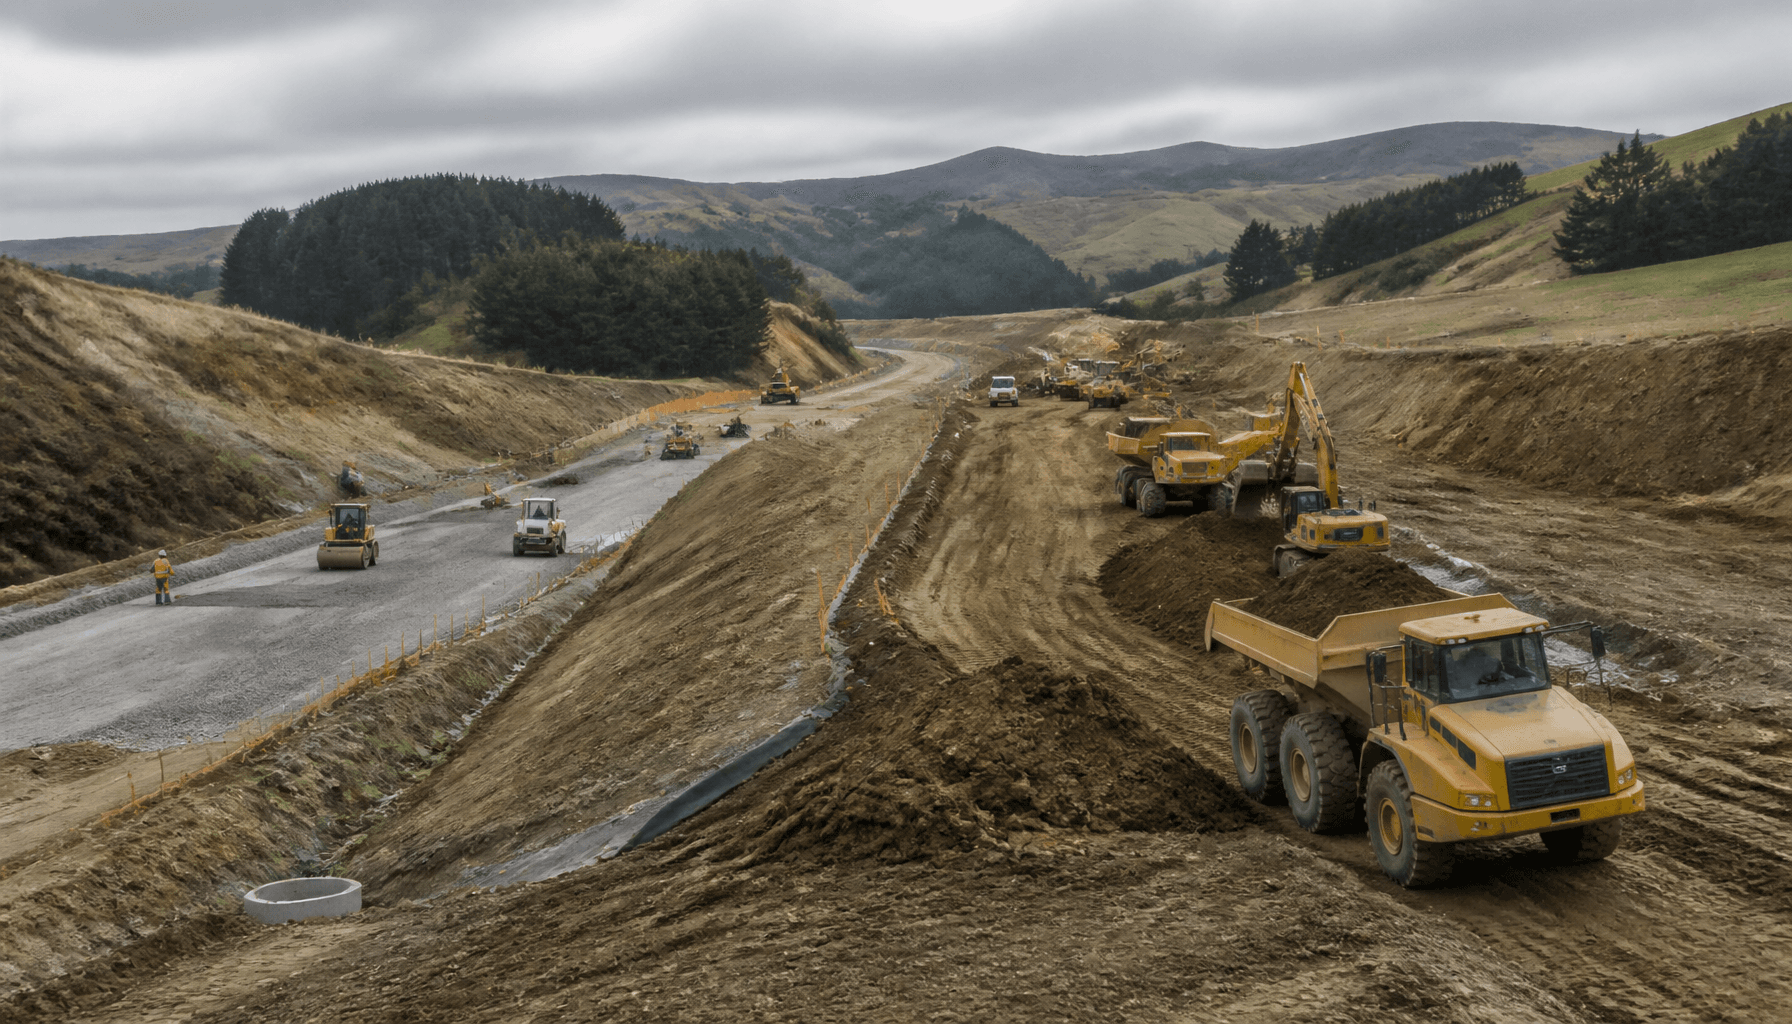
Infrastructure work already in construction held steady at $71.2 billion. Completions were replaced by new starts. About $17.5 billion of initiatives are scheduled to enter construction within 12 months. Eighty-nine per cent of that cohort has full, partial or confirmed funding.
Projected spend over the next 12 months for initiatives with committed or confirmed funding is $18.6 billion — about 4.2% of GDP. Fully funded initiatives alone project $13.3 billion, or 3% of GDP. New Zealand has spent an average 5.8% of GDP on infrastructure over the past 20 years, so the pipeline still under-captures total national activity.
Transport dominates the forward profile: $9.6 billion, or 46%, of projected spend in the next 12 months, and $62.6 billion, or 47%, of all-sector projected spend over 10 years. Water is second at $4.7 billion (22%) in the near-term year.
Of the $95.8 billion fully funded stock, Te Waihanga modelling estimates about $51.5 billion has already been spent on those active projects.
Budget 2026 and the capital path
The June snapshot lands after Budget 2026 on 28 May. The Budget set a net capital package of about $5.7 billion and pointed to around $60 billion of infrastructure spend over four years from existing and new funding. Named items include about $1.8 billion for the Cambridge to Piarere Expressway, $400 million for state highway resilience, $705 million capital plus $477 million operating for rail renewals, and health capital including Whangārei hospital works.
In July the Government and NZTA released the Major Transport Projects Pipeline, phasing Roads of National Significance and major public transport projects. Those phasing decisions feed the National Infrastructure Pipeline through quarterly NZTA updates. Funding-status shifts in the pipeline are how Budget and agency choices show up for the market.
On 16 June the Government formally responded to the National Infrastructure Plan, supporting all 16 Te Waihanga recommendations, three in principle. Implementation — not another catalogue — is the open fiscal question.
Industry and the wider construction setting
Infrastructure New Zealand chief executive Nick Leggett welcomed the Plan response but pressed the funding point hard.
The Pipeline is useful, but it cannot just be a wish list. Industry needs more clarity on what is likely to go ahead, and that what is contained in any pipeline, is funded and therefore will be delivered.
Leggett also argued fiscal discipline cannot substitute for growth-oriented investment: "Fiscal discipline matters, but we cannot cut our way out of an infrastructure deficit."
Broader building activity remains soft. Stats NZ’s March 2026 quarter showed a 3.5% fall in seasonally adjusted building volume — the fourth consecutive quarterly decline — and building work value of $7.2 billion, down 5.9% year-on-year. MBIE’s late-2025 National Construction Pipeline Report still had total construction dipping in 2025 before recovering toward 2030, with infrastructure the steadier component. Quantity surveyor RLB has described infrastructure as outperforming other construction segments, with civil cost inflation expected to peak near 5% late 2026 before easing.
Te Waihanga notes that around one-third of the wider construction workforce works in infrastructure. The $71.2 billion under-construction stock and the $17.5 billion 12-month start signal are therefore material for plant, labour and bid capacity across New Zealand contractors.
What to watch
Headline pipeline value and fully funded dollars are rising. Under-construction work is stable at a high level. Yet a large share of the stock remains unfunded or only partly funded, and 21 megaprojects above $1 billion still lack a confirmed funding source. Funding those without offsets would pressure net debt and interest costs. Leaving them unfunded leaves the headline inflated relative to deliverable work.
The next quarters will test conversion of the $17.5 billion construction-entry cohort and Budget 2026 projects into contracts. Fiscal discipline means ranking megaprojects against each other and against the smaller, better-funded flow that keeps regional markets busy — not treating a longer list as progress by itself.