IRD to Consult Further on GST Act Modernisation — Economic News
TAX POLICY · GST ACT MODERNISATION
IRD Signals Further Consultation on Targeted GST Act Updates
Inland Revenue will conduct additional stakeholder consultation on proposals to modernise the Goods and Services Tax Act, a 20 November 2026 NBR report confirmed, citing resource constraints that rule out a full rewrite.
Cabinet has approved the transfer of any remaining assets and obligations from New Zealand Green Investment Finance to Crown Regional Holdings Limited, New Zealand Growth Capital Partners, Aspire NZ Seed Fund and Treasury.
New Zealand risks forgoing $11 billion to $12 billion in Emissions Trading Scheme auction revenue by 2035 without major reforms, according to a Motu Economic and Public Policy Research report released this month.
The Crown recovered more than $500 million in capital after New Zealand Green Investment Finance Limited completed transfers of its residual assets and obligations on 16 October 2026.
Inland Revenue will conduct additional stakeholder consultation on proposals to modernise the Goods and Services Tax Act. A 20 November 2026 NBR report confirmed the plans. Officials cited resource constraints that rule out a full rewrite of the legislation.
The department released its 'Current GST issues' officials' issues paper on 22 May 2026. Public consultation closed on 29 June 2026. Thirty-six submissions were received. The 87-page document posed 56 questions across eight problem areas.
Officials concluded that core policy settings remain effective. A full rewrite carried unacceptable risks of unintended consequences and drafting delays. The preferred approach focuses on a controlled refresh.
Modernisation steps include renumbering provisions after removing obsolete ones. Complex sections will be broken into smaller units. Administrative rules will move to the Tax Administration Act 1994. Defined-terms lists and reader aids such as examples and diagrams will be added.
The Annual Rates Bill items
A 16 July 2026 tax policy report to Revenue Minister Simon Watts recommended specific items for the 2026–27 Annual Rates Bill. These cover electricity exported to the grid by residential premises, correction of errors and inaccuracies, and pre-registration expenditure deductions. The changes project a modest net revenue gain of $6.676 million over the forecast period.
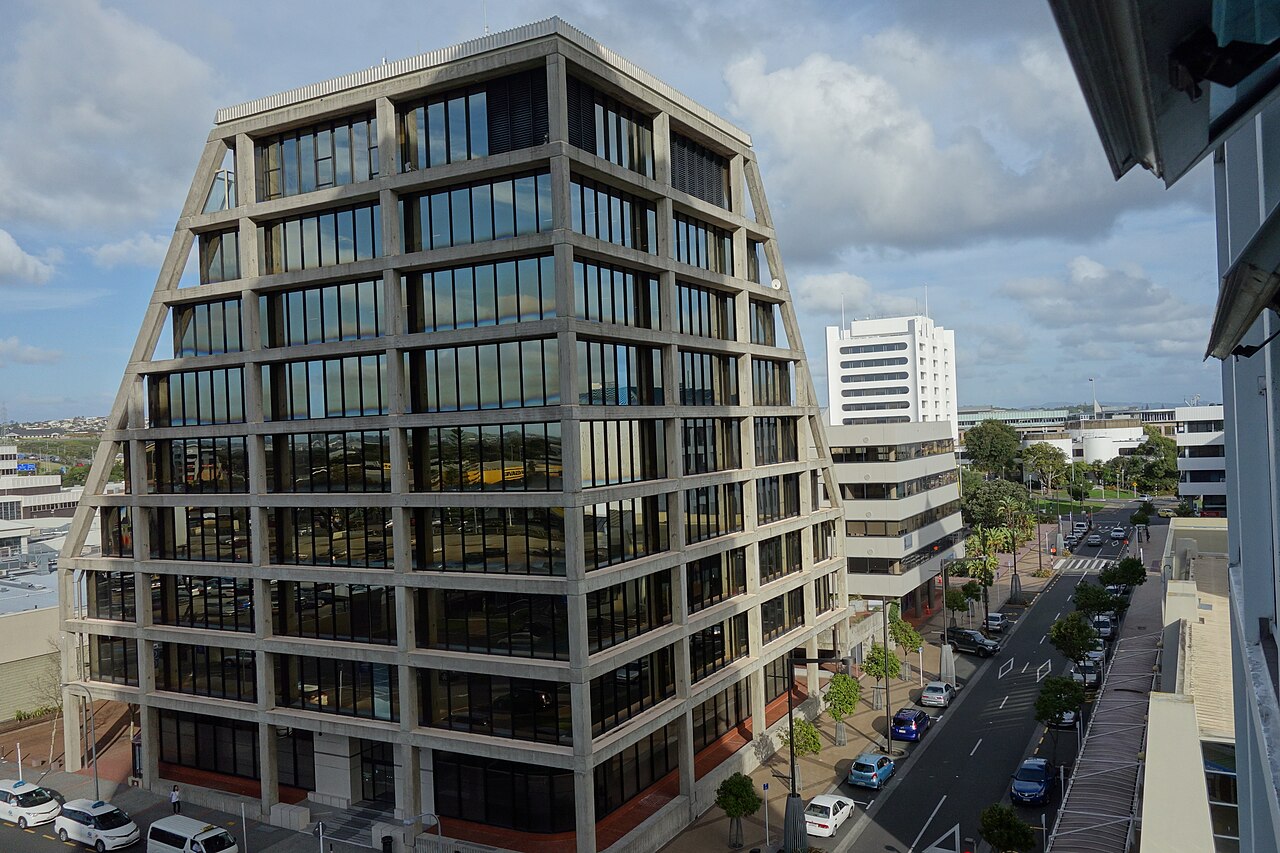
An Inland Revenue Department office. IRD says it lacks the resources for a full rewrite of the GST Act and will instead pursue targeted modernisation.
GST was introduced in New Zealand on 1 October 1986. The Act has undergone repeated amendments, including major rounds in 1996, 2000 and 2011. The result is a longer, denser statute that raises compliance costs for businesses.
The broad base and single 15 per cent rate continue to function effectively. Targeted fixes aim to reduce interpretation disputes and lower voluntary compliance costs for the hundreds of thousands of GST-registered entities, particularly small and medium enterprises.
Sector reaction
Sector reaction has involved professional bodies including Chartered Accountants Australia and New Zealand and firms such as Deloitte. The accommodation sector has particular interest in proposals that would reclassify certain student accommodation as commercial dwellings while exempting more transitional and social housing.
Submissions on the issues paper were generally supportive of the technical proposals.
Some disagreement emerged on specific remedies such as the treatment of pre-registration expenditure below the $10,000 threshold.
What happens next
IRD plans further consultation following the 2026 issues paper process. The timing aligns with ongoing compliance work on digital platforms and confirmation that zero-rating inbound tourism GST is not under active consideration.
The incremental approach balances fiscal discipline with practical improvements to the tax system. Clearer legislation should reduce administration burdens on Inland Revenue and compliance costs on businesses over the medium term.