Foley Wines Triples Profit with Premium Strategy Amid Sector Rebalancing
Foley Wines Limited reported net profit after tax of $2.937 million for the year ended 30 June 2026, more than tripling from the prior year's loss of $1.857 million. The company achieved this through a focused premiumisation strategy and cost discipline even as bottled case sales declined 9.5 percent to 552,000 cases.
New tenancy rents in New Zealand rose about 1 percent year on year in recent data, according to ANZ senior economist Matthew Galt, even as national house prices fell for the seventh consecutive month in October 2026.
New Zealand's economy expanded 2.6 percent in the year to June 2026, the strongest annual pace since mid-2023, according to Stats NZ data. Yet households and domestic businesses continue to face high inflation, a soft labour market and weak house prices, Westpac NZ chief economist Kelly Eckhold said.
Land values on Hawke's Bay's Heretaunga Plains have halved in some cases amid water insecurity and stalled consents. Regulatory uncertainty from the TANK plan and RMA transition now imposes clear economic costs on one of New Zealand's key growing regions.
Foley Wines Limited reported net profit after tax of $2.937 million for the year ended 30 June 2026, more than tripling from the prior year's loss of $1.857 million. The company achieved this through a focused premiumisation strategy and cost discipline even as bottled case sales declined 9.5 percent to 552,000 cases.
Foley Wines Delivers Strong Turnaround
Foley Wines Limited posted net profit after tax of $2.937 million for the year ended 30 June 2026. This marked a 258.2 percent increase from the $1.857 million loss in the prior year. Bottled sales revenue fell 5.4 percent to $62.8 million while case volumes dropped 9.5 percent to 552,000. Operating earnings rose 323.5 percent to $5.878 million. Operating EBITDA increased 22.8 percent to $15.502 million.
The board maintained a fully imputed final dividend of 2 cents per share. Basic earnings per share reached 4.47 cents compared with a loss of 2.83 cents the previous year. CEO Mike Higgins described the period as a year of progress in a very challenging economy.
The Drivers Behind the Result
Foley Wines pursued premiumisation by shifting sales toward higher-value packaged wines rather than chasing volume. Average revenue per case rose even as total cases fell. The company protected margins through strong distribution partnerships and targeted promotional investment. Inventory stayed balanced, enabling early shipments of the 2026 vintage.
Cost discipline played a key role. Reduced interest and administration costs combined with winery and viticulture efficiencies. These steps offset the impact of a competitive global market marked by oversupply from the 2025 bumper harvest.
“It's been a year of progress in a very challenging economy. Operating EBITDA is up 22.8%, while bottled case sales were down 9.5% on the previous year's record sales. A bumper 2025 harvest and a well-documented oversupply of New Zealand wine resulted in a very competitive marketplace and deep discounting, but our premiumisation strategy and strong distribution partnerships continue to create opportunities for the Company.”
Regional performance varied sharply. UK and Europe delivered the only growth at plus 2 percent. China continued its expansion. Australia saw a 26 percent decline and the US a 10 percent drop. Asia Pacific fell 21 percent while New Zealand domestic sales declined 4 percent.
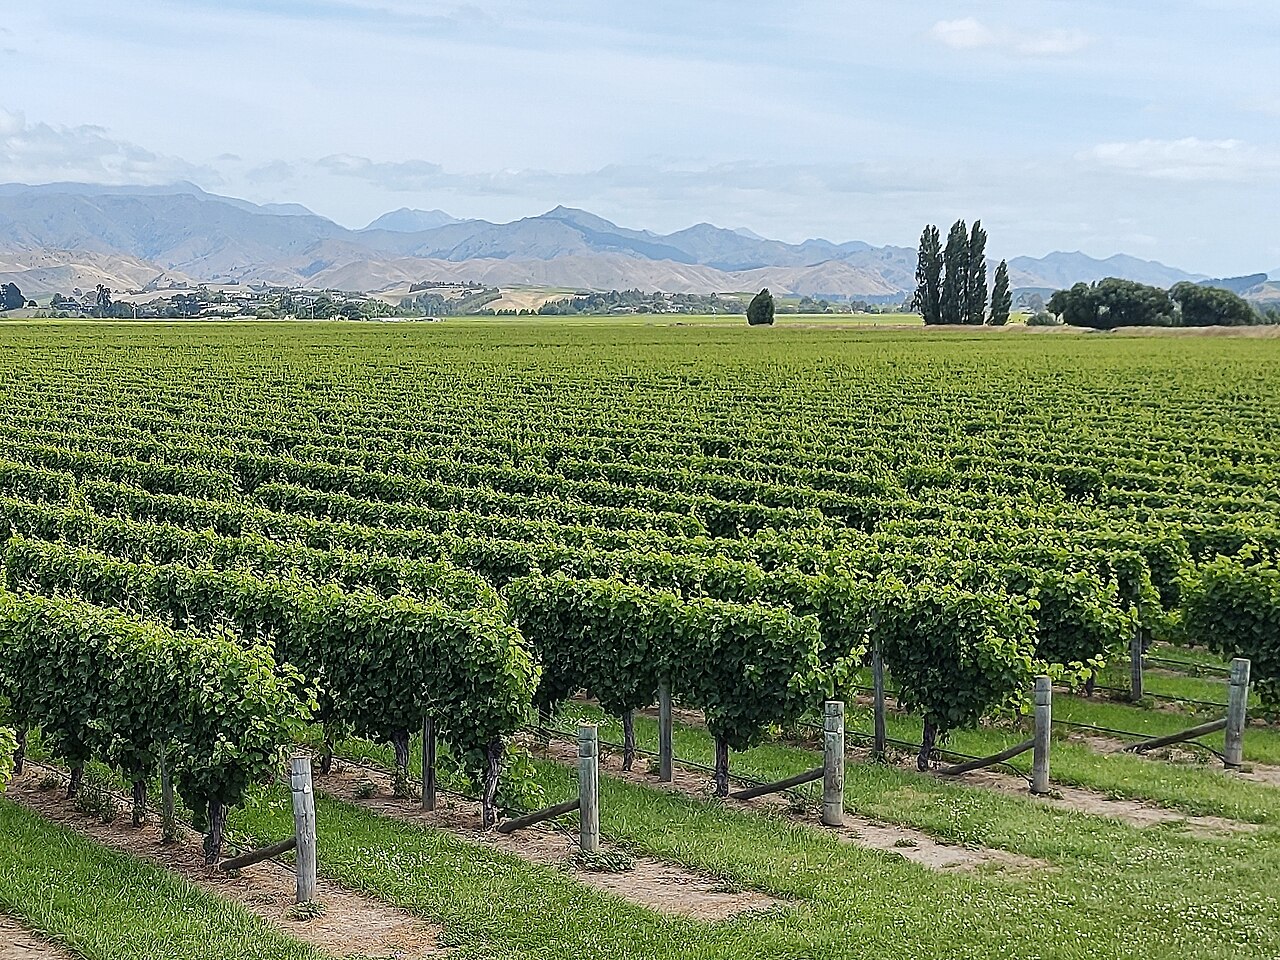
Vineyards in Marlborough's Wairau Valley, part of the regional wine economy affected by the sector's 2,000-hectare vineyard pullback.
Trade-Offs in the Premium Approach
The strategy traded volume for margin. Total bottled revenue declined 5.4 percent to $62.8 million. If competitors capture shelf space with discounted wines, Foley could face higher costs to regain position later. The approach holds while premium demand remains steady.
China growth of 72 percent in industry volumes brings concentration risk. New Zealand has faced sudden tariff disruptions on other exports in the past. Deepening exposure there while US volumes weaken shifts rather than removes geographic risk.
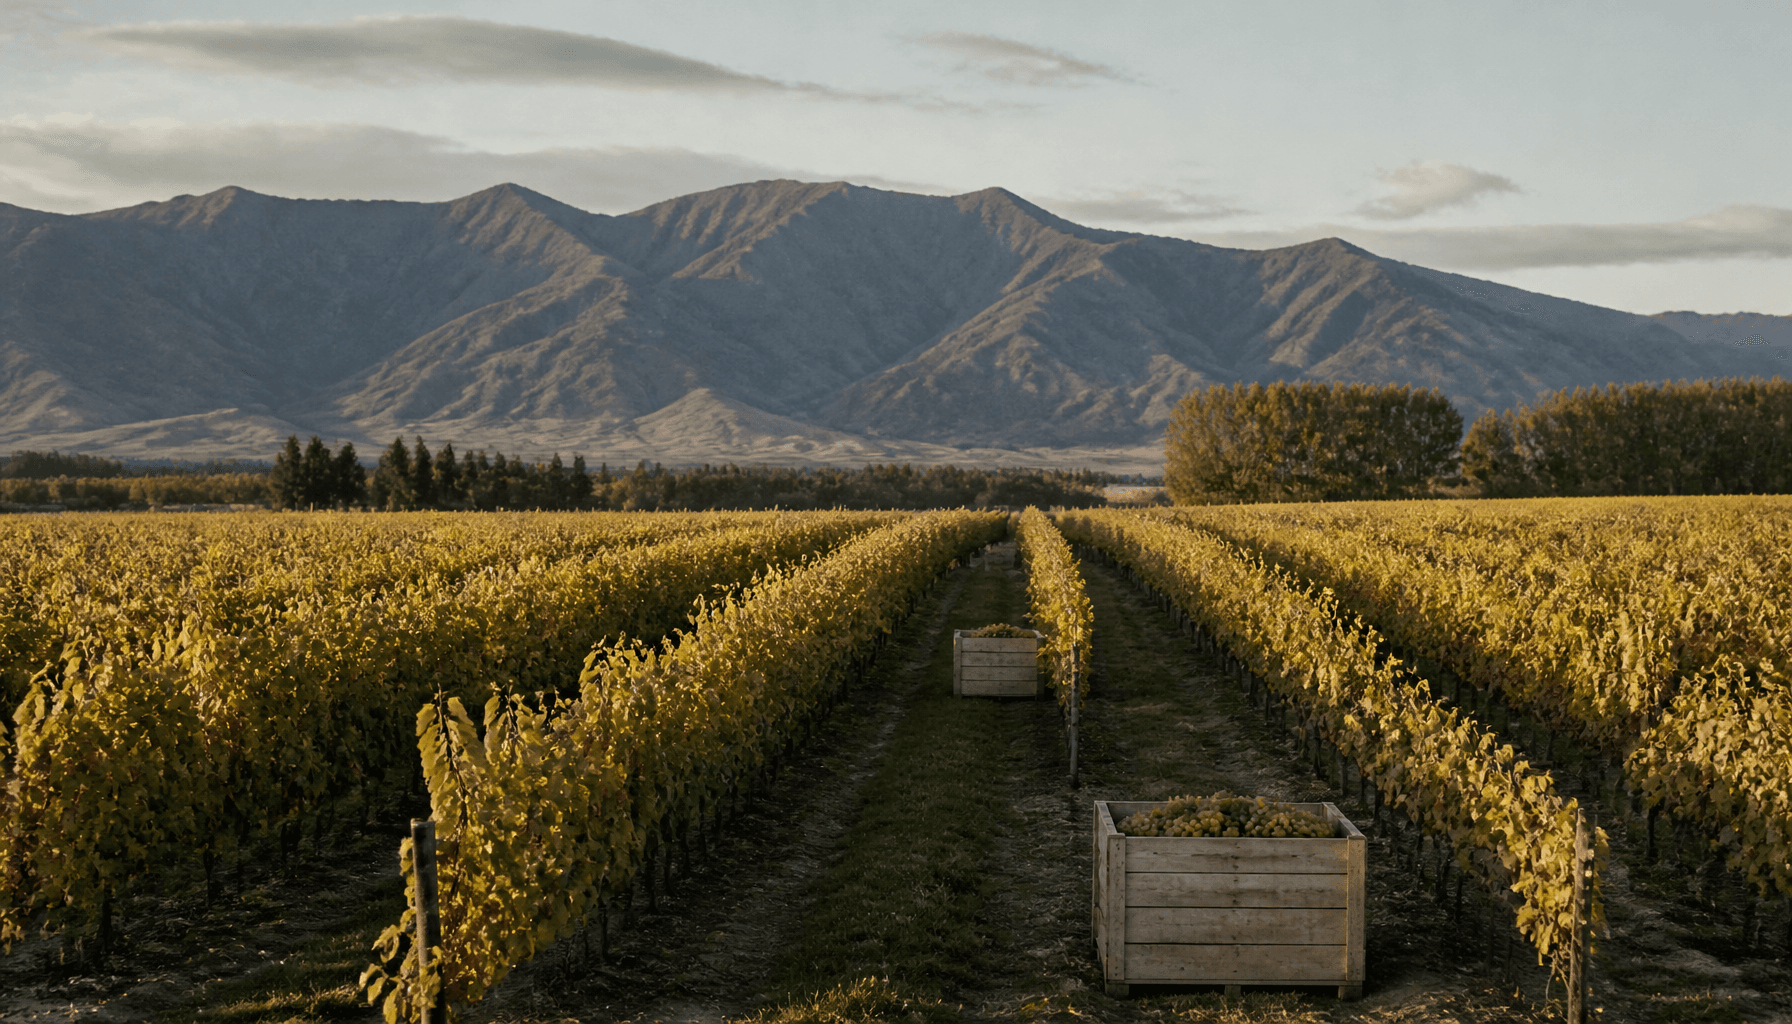
The 15 percent smaller 2026 harvest of approximately 440,000 tonnes supports future pricing power. It also means less product available for sale in the near term. The removal of about 2,000 hectares of vineyards nationwide, including a 46 percent reduction in Gisborne, represents permanent capacity loss that cannot be reversed quickly if demand rebounds.
Maintaining the 2 cents per share dividend signals board confidence. It also uses cash that could fund further distribution investment or sustainability projects. At the current share price of 55 cents, the yield appeals to retail investors and creates pressure to sustain payouts.
Second-Order Effects on the Broader Economy
Grape growers on volume-based contracts face lower income as wineries reduce purchased tonnage. Vine removals reflect some growers exiting rather than waiting for prices to recover. This leads to permanent contraction in regional economies such as Gisborne and parts of Hawke's Bay.
Logistics, packaging and bottling suppliers experience lower demand. Employment effects appear in Nelson and Marlborough industrial and transport sectors.
If other producers imitate Foley's premiumisation, collective price repositioning could lift New Zealand wine's global anchor. It could also cede mid-price volume to lower-cost competitors from South America and South Africa.
The New Zealand-India Free Trade Agreement opens a potential growth market. India's expanding middle class shows appetite for imported wine at price points that fit premium positioning. Tourism revenue from brand homes and events such as Toast Martinborough depends on domestic confidence and international visitor flows.
The share price at 55 cents, down 8 percent year on year, indicates investors discount either the sustainability of margin gains, the small absolute profit base relative to $62.8 million revenue, or liquidity constraints on small-cap re-rating.
Historical Context and Market Signals
New Zealand wine exports reached $2.108 billion in value and 306.2 million litres in volume for the 12 months to June 2026. Value growth was marginal at around 0.5 percent while volumes rose 8 percent. This reflects lower average returns per litre across the sector.
The current oversupply episode echoes the mid-2000s Marlborough expansion. Earlier adjustment came through export diversification and brand investment rather than price competition. The present situation differs because of secular declines in alcohol consumption in key markets.
Australian producers faced sudden loss of China access after 2020 tariffs. They redirected volumes at lower prices and compressed margins for years. New Zealand benefited then and now faces similar demand softness in its own markets.
Foley Wines bottled case sales by region, FY2026
Region
Cases (change YoY)
New Zealand
164,000 (-4%)
UK/Europe
147,000 (+2%)
USA
103,000 (-10%)
Australia
76,000 (-26%)
Asia/Pacific
58,000 (-21%)
Case sales diverged sharply by market, with UK/Europe the only growth region.
Source: Foley Wines Limited Annual Report 2026
Counter-Argument and Evidence
Aggregate export data show value growth lagging volume growth. New Zealand Winegrowers promotes premium positioning, yet the sector as a whole has not yet captured premium returns. Foley's result stands as an outlier rather than a sector-wide outcome.
Evidence for the premium strategy rests on Foley's specific margin protection and inventory balance. Operating EBITDA rose despite the volume drop. The smaller 2026 harvest and industry vine removals reduce future oversupply pressure. These factors support pricing power for disciplined producers.
Open Questions for the Sector
Demand recovery pace in Australia and the United States remains uncertain. Tariffs continue as a headwind in the US. Consumer shifts away from alcohol in mature markets could persist.
The next data prints on export volumes and values for the December 2026 half year will show whether Foley's pattern spreads. Industry projections target $2.5 billion in exports by 2030 under favourable conditions.
Outlook for NZ Wine Exporters
Foley's results demonstrate that private-sector cost control and premium positioning can deliver profitability gains amid industry rebalancing. The approach aligns with market signals rather than volume targets. Continued investment in China and plans for US growth through Foley Family Wines USA fit export diversification goals. Stronger profitability at premium-focused firms supports capital investment in sustainability that underpins New Zealand's international reputation. Risks from pricing pressure and slower demand recovery in key markets remain material to the broader export earnings trajectory.