RBNZ Holds OCR at 2.75% in 4-3 Split Decision, Pausing Tightening Cycle
The Reserve Bank of New Zealand's Monetary Policy Committee voted 4-3 on 28 October 2026 to hold the Official Cash Rate at 2.75%, defying market expectations of a 25 basis point hike to 3.00%. The decision underscores internal divisions on whether recent fuel-driven inflation pressures warrant immediate pre-emptive action or a pause to assess transmission of the July and September increases.
The Reserve Bank of New Zealand's Monetary Policy Committee delivered a 4-3 surprise hold on the official cash rate at 2.75 per cent on 28 October 2026, defying near-universal expectations of a 25 basis point rise and triggering an immediate 1.3 per cent drop in the New Zealand dollar to 56.1 US cents.
The Reserve Bank of New Zealand is expected to raise the Official Cash Rate by 25 basis points to 3.00 per cent on 28 October 2026, the third consecutive increase in a tightening cycle that began in July.
The Sharesies Index of investor confidence averaged 38 in the September 2026 quarter, down from 57 in the June quarter, as the Reserve Bank of New Zealand raised the official cash rate twice and annual CPI inflation hit 4.1 percent driven by higher fuel prices.
The Reserve Bank of New Zealand's Monetary Policy Committee voted 4-3 on 28 October 2026 to hold the Official Cash Rate at 2.75%, defying market expectations of a 25 basis point hike to 3.00%. The decision underscores internal divisions on whether recent fuel-driven inflation pressures warrant immediate pre-emptive action or a pause to assess transmission of the July and September increases.
Hold votes came from Governor Anna Breman, Carl Hansen, Prasanna Gai and Rebecca Williams, according to the RBNZ's OCR decision release, while Paul Conway, Hayley Gourley and Karen Silk voted for a hike to 3.00%.
The drivers
The September 2026 quarter CPI print showed annual inflation easing to 3.7% from 4.1% in June, below forecasts, according to Stats NZ. Petrol prices fell 6.5% quarterly but remained 19.1% higher year-on-year, accounting for 17.5% of the annual CPI rise. The RBNZ noted this relief is temporary, projecting inflation rebounding to 4.4% in the December quarter based on oil futures.
Core measures have climbed toward the upper end of the 1-3% target band. Price increases have become more broad-based, with 56% of the CPI basket rising more than 3% annually, per the RBNZ Record of Meeting. The NZD trade-weighted index has declined approximately 3% since early September, amplifying imported inflation risks from fuel and other goods.
Wage growth remains subdued and medium-term inflation expectations anchored. The economy shows export-led resilience but domestic demand and labour market recovery are uneven. All MPC members agreed further tightening will likely be needed, but they diverged on timing.
The trade-offs
Holding provides time to observe how the two prior 25bp hikes transmit through wholesale rates, lending, and deposit pricing. Major banks typically adjust retail rates within days of OCR moves. A pause delays upward pressure on floating mortgages and business lending, offering short-term relief to indebted households and firms amid elevated living costs.
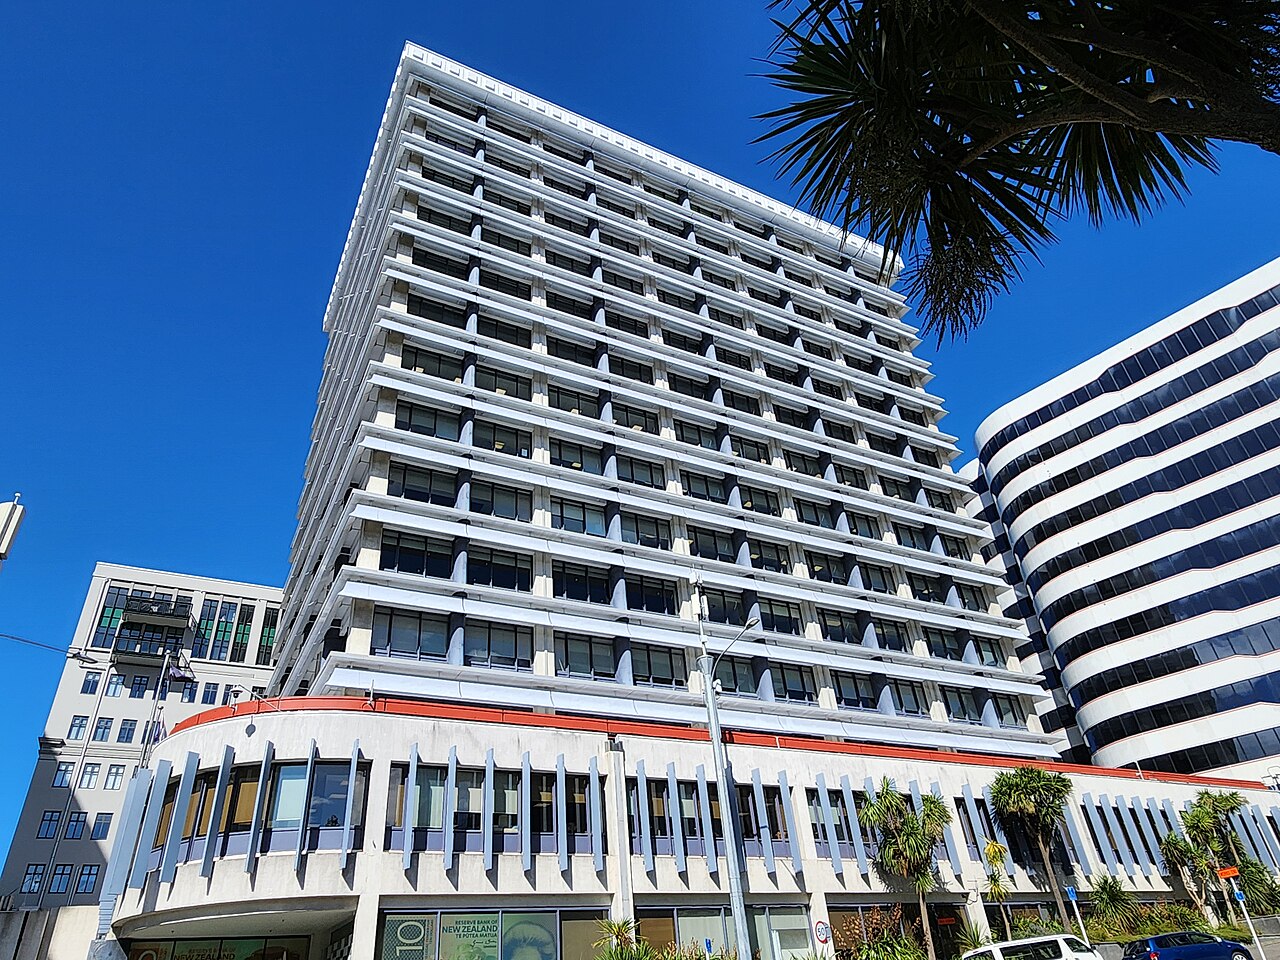
The Reserve Bank of New Zealand, whose Monetary Policy Committee voted 4-3 to hold the OCR at 2.75% rather than deliver a widely expected hike.
The risk is that pausing allows second-round effects to build if high energy costs persist. The RBNZ highlighted risks of broad-based price pressures entrenching if the temporary fuel lull reverses as projected. Pre-decision pricing had reflected near-certainty of tightening, with economists at BNZ, ASB, ANZ and the NZIER Shadow Board recommending a hike.
the committee is not on a preset course and timing of further adjustments is highly uncertain — Anna Breman, RBNZ Governor
Second-order effects
Fixed mortgage rate repricing faces delayed upward pressure. With 40-50% of mortgages on floating or short-fixed terms due to reprice, the hold provides breathing room. However, if the December MPS signals a steeper track, fixed rates could rise sharply in one adjustment.
Housing and construction sentiment may interpret the pause as confirmation of a shallower endpoint, supporting modest recovery in building consents. Export sectors benefit from a weaker NZD, improving competitiveness for dairy, meat and tourism. Firms absorbing cost pressures face margin compression risks if demand stays subdued, potentially affecting investment and employment intentions over 12-18 months.
The December 9 Monetary Policy Statement becomes the key event to watch, with a revised OCR track and inflation forecasts due. A lower OCR path modestly reduces government debt servicing costs on floating-rate Crown borrowing.
Historical context
The closest analogue is the RBNZ's October 2015 hold amid commodity price volatility. Markets had priced further cuts; the pause allowed assessment before resuming easing in December. The 2026 pause mirrors the data-dependent approach but occurs in a hiking cycle, where the cost of delay is prolonged above-target inflation rather than disinflation.
The RBA's May 2023 resumption after an April pause and the Fed's June 2023 'skip' provide further parallels. The RBNZ language conditions future action on evolving data while preserving a tightening bias.
The counter-argument
Three MPC members prioritised pre-emptive action against core inflation risks, arguing the upside surprises in fuel and NZD warranted an immediate hike. BNZ senior economist Doug Steel noted oil prices much higher and the NZD materially lower than September assumptions. ASB senior economist Mark Smith cited upside risks too high to ignore. The split reveals genuine uncertainty on whether the dominant risk is temporary or entrenching.
Open questions
The December MPS will clarify the Committee's revised projections. Data on December quarter CPI, wage outcomes and export performance will shape whether the pause proves a one-meeting delay or signals reassessment of the tightening endpoint. Regional disparities, with export areas faring better than domestic-demand regions, warrant monitoring.
The decision leaves policy accommodative relative to neutral estimates, with global risks from geopolitics, energy volatility and AI-driven capital demands adding uncertainty.