RBNZ Poised to Lift OCR to 3 Per Cent Amid Persistent Fuel Inflation
The Reserve Bank of New Zealand is expected to raise the Official Cash Rate by 25 basis points to 3.00 per cent on 28 October 2026, the third consecutive increase in a tightening cycle that began in July.
The Reserve Bank of New Zealand's Monetary Policy Committee delivered a 4-3 surprise hold on the official cash rate at 2.75 per cent on 28 October 2026, defying near-universal expectations of a 25 basis point rise and triggering an immediate 1.3 per cent drop in the New Zealand dollar to 56.1 US cents.
The Reserve Bank of New Zealand's Monetary Policy Committee voted 4-3 on 28 October 2026 to hold the Official Cash Rate at 2.75%, defying market expectations of a 25 basis point hike to 3.00%. The decision underscores internal divisions on whether recent fuel-driven inflation pressures warrant immediate pre-emptive action or a pause to assess transmission of the July and September increases.
The Sharesies Index of investor confidence averaged 38 in the September 2026 quarter, down from 57 in the June quarter, as the Reserve Bank of New Zealand raised the official cash rate twice and annual CPI inflation hit 4.1 percent driven by higher fuel prices.
The Reserve Bank of New Zealand is expected to raise the Official Cash Rate by 25 basis points to 3.00 per cent on 28 October 2026, the third consecutive increase in a tightening cycle that began in July.
RBNZ Set to Act on Fuel-Driven Inflation
The Reserve Bank of New Zealand is expected to raise the Official Cash Rate by 25 basis points to 3.00 per cent at its 28 October 2026 Monetary Policy Review. This move would mark the third consecutive hike in a tightening cycle that started in July 2026. The decision comes just ten days before the 7 November general election.
Economists across major banks forecast the increase despite earlier signals that might have suggested a pause. The primary driver remains higher fuel prices linked to global oil market pressures earlier in the year. Stats NZ data show petrol prices rose 19.1 per cent over the year to September 2026.
The Inflation Picture
Headline CPI eased to 3.7 per cent year-on-year in the September quarter from 4.1 per cent in June. Yet underlying pressures persist. Petrol accounted for 17.5 per cent of the annual CPI increase. Without the petrol effect, inflation would have been 3.2 per cent according to Stats NZ.
Quarterly petrol prices fell 6.5 per cent in September after a sharp rise in June. However, recent global oil price resurgence and a weaker New Zealand dollar are expected to push annual inflation back above 4 per cent by year end. ASB forecasts 4.7 per cent for the December quarter.
Broader contributors include international airfares up 14.3 per cent quarterly and electricity prices rising 9.3 per cent annually. Core measures stay firmer, with non-tradables inflation at 3.3 per cent and tradables at 4.3 per cent year-on-year.
Recent CPI and Petrol Contribution
Fuel prices remain a key driver of headline inflation despite the September dip.
Source: Stats NZ Consumers Price Index September 2026 quarter
RBNZ Mandate and Independence
The Reserve Bank operates under a clear mandate to keep inflation within the 1 to 3 per cent target band, with a focus on the 2 per cent midpoint. Its September 2026 Monetary Policy Statement set policy to return inflation to that midpoint by late 2027. The Committee raised the OCR to 2.75 per cent in September by consensus after the July move to 2.50 per cent.
No statutory requirement exists for the Bank to consider political calendars. Commentators note that delaying a data-supported hike would itself introduce political considerations. The Bank's independence allows it to prioritise price stability over short-term electoral dynamics.
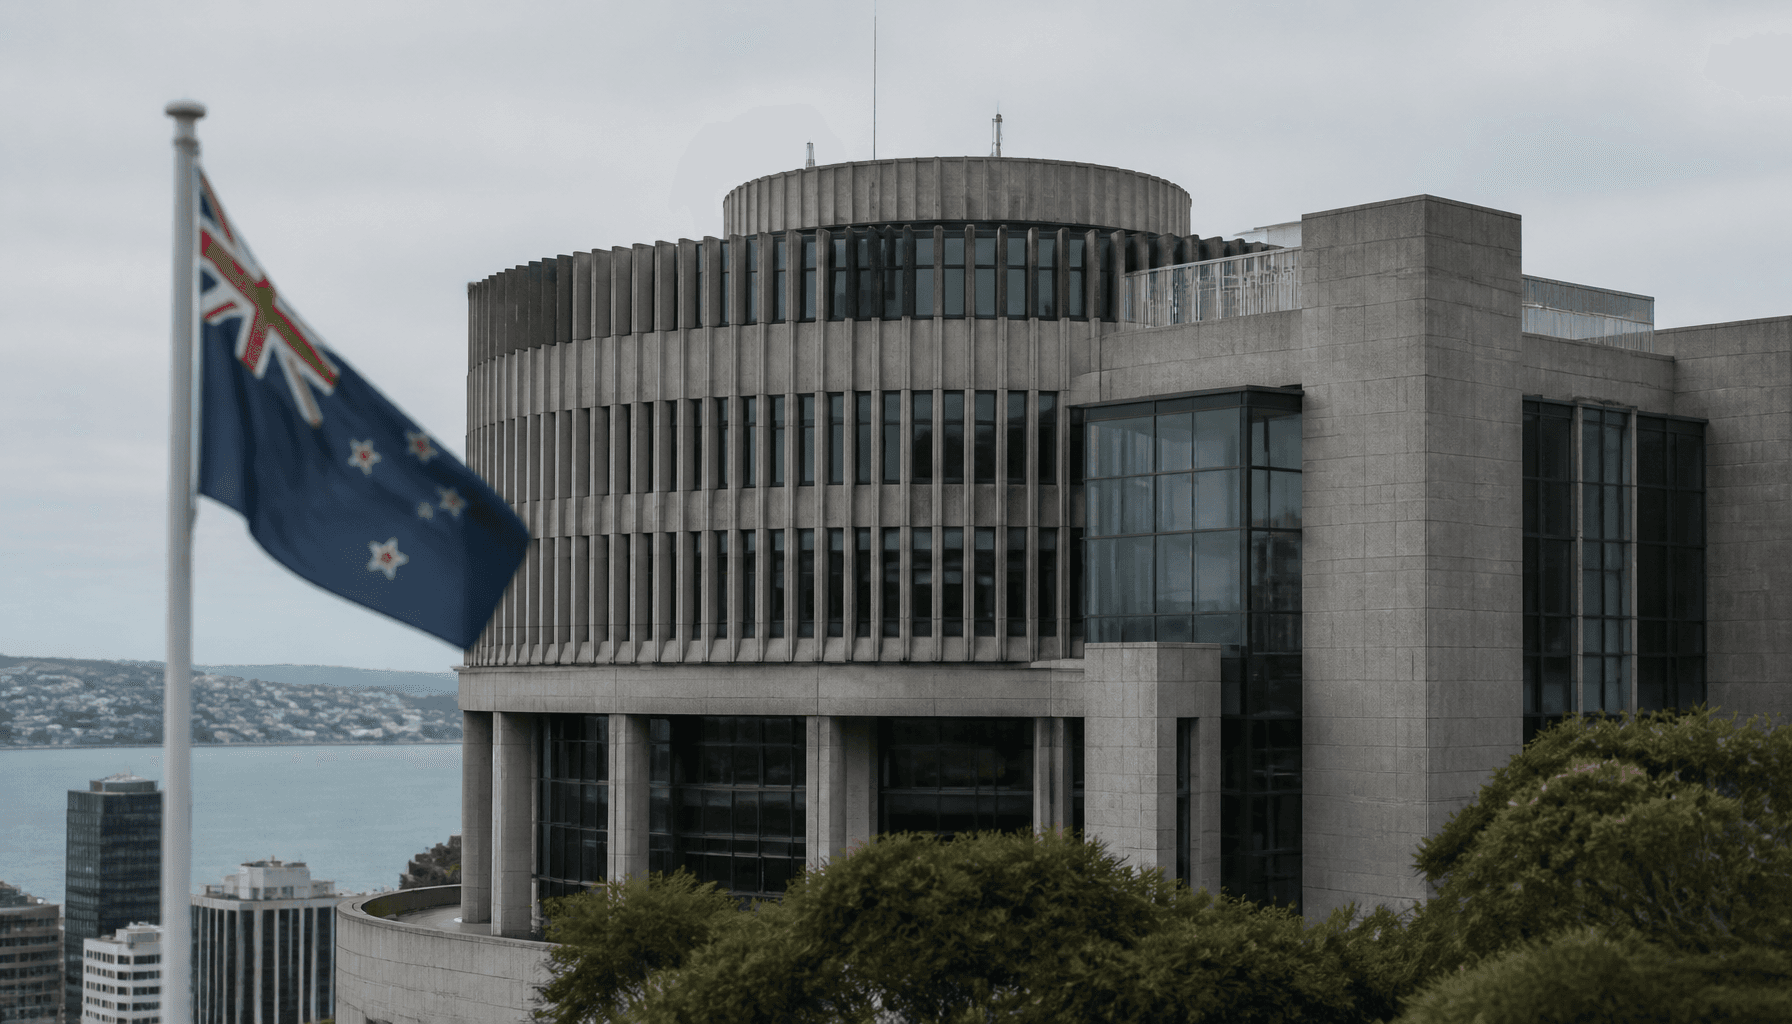
The Reserve Bank of New Zealand in Wellington, where the Monetary Policy Committee is expected to lift the OCR to 3.00 per cent on 28 October.
Historical Precedents
Rate changes during election periods are not unprecedented. The Reserve Bank raised the OCR by 25 basis points in July 2014 ahead of the September election. A 50 basis point hike occurred ten days before the November 1999 election. A 100 basis point cut took place weeks before the 2008 election during the global financial crisis.
Earlier elections were generally less closely contested than the current one. This reduces direct political sensitivity in past cases while the institutional precedent remains clear: the Bank acts when inflation or growth conditions require.
Macroeconomic Setting
Real GDP grew 0.2 per cent in the June 2026 quarter, with annual growth revised to 2.6 per cent, above the Treasury Budget forecast of 1.8 per cent. Growth concentrated in exports and construction while domestic demand stayed subdued. The Reserve Bank expects activity to strengthen and broaden, with spare labour market capacity limiting wage pressures.
Australia's RBA cash rate sits in the 4.35 to 4.60 per cent range, higher than New Zealand's trajectory. This reflects differing inflation and growth paths between the two economies.
Mortgage and Household Impacts
Floating mortgage rates already stand at 6.29 per cent, with fixed rates rising. Westpac and ASB note that fixed rates have passed cycle lows. The October hike will anchor wholesale rates higher, increasing borrowing costs for households re-fixing in coming months.
Savers benefit from higher deposit rates. First-home buyers and investors face compressed affordability. This transmission channel operates with a lag as many mortgages remain fixed, but the signal affects expectations and future re-pricing.
Economist Consensus
Westpac chief economist Kelly Eckhold expects the 25 basis point October hike and further rises to a peak of 4 per cent in 2027. ASB senior economist Mark Smith forecasts the move to 3 per cent on 28 October, plus additional hikes in December and February to a 3.5 per cent peak. ANZ and BNZ analysts align with further tightening into 2027.
Kiwibank remains more cautious on downside growth risks. Analyst forecasts converge on a terminal rate between 3.5 and 4 per cent.
Trade-Offs in Policy
Tighter policy anchors inflation expectations and curbs imported inflation through currency effects. It supports New Zealand dollar stability. Yet higher rates dampen the modest GDP growth trajectory, particularly where private consumption remains flat.
Fiscal costs rise through government debt servicing on floating-rate obligations. Slower nominal GDP growth compresses the tax revenue base. Treasury monitors these interactions in its investor updates.
Second-Order Effects
Higher borrowing costs may moderate house price pressures, a political issue, but could also slow construction activity when supply shortages persist. Retail and regional economies outside agriculture and tourism hubs may feel further strain as discretionary spending weakens.
Bank net interest margins improve while credit availability could tighten if demand softens. Wage-price spiral risks rise if fuel costs feed into transport and construction, shifting two-year inflation expectations upward.
Forward Risks
The post-decision statement will clarify whether the Bank signals a conditional pause or commits to further hikes. Year-end CPI prints due early 2027 will test forecasts of 4.7 per cent. Global oil prices and New Zealand dollar movements remain key variables.
The New Zealand dollar to Australian dollar cross-rate response will influence capital flows and import costs. Business and consumer survey data on inflation expectations will indicate whether de-anchoring risks have materialised.
The Reserve Bank's data-dependent approach prioritises medium-term price stability. Households and businesses should prepare for sustained higher borrowing costs through 2027.