Wellington’s ASB last place: fiscal drawdown, housing hole and two-speed NZ
ASB’s Q2 2026 Regional Economic Scoreboard left Wellington joint last with Gisborne while Canterbury led on dairy cash, jobs and retail. The capital’s multi-quarter underperformance is structural: public-service consolidation, a deep housing correction and stalled population growth colliding with a national OCR still set for nationwide inflation.
New Zealand rural confidence stayed positive for a ninth straight quarter in August 2026, with horticulturalists overtaking sheep and beef as the most optimistic sector while investment plans stayed soft.
MBIE’s 6 September snapshot shows 51.7 days of petrol cover on paper. Only 34.5 of those days sit onshore. Eight of nine ships still float outside the EEZ, and sequential Hormuz then Red Sea stress is already priced into $3-plus petrol.
Higher distribution and transmission charges accounted for 54% of the 6.8% average power-price rise for households and small businesses in the first half of 2026, Electricity Authority retailer data show, as Commerce Commission revenue paths and a multi-decade electrification bill keep network costs rising.
ASB’s latest Regional Economic Scoreboard for the June 2026 quarter placed Wellington joint last among New Zealand’s 16 regional council areas, tied with Gisborne. Canterbury ranked first. Taranaki and Southland filled second and third.
The scoreboard is not a GDP league table. It is a composite of timely quarterly indicators — employment, construction, retail trade and house prices — designed to show relative momentum. For the capital the message is blunt. Population growth has stalled. House prices sit roughly 26–30 percent below the 2021 peak. Construction remains thin. Retail is soft.
ASB acting chief economist Kim Mundy framed a two-speed economy. Export- and primary-linked regions are carrying growth. North Island urban domestic-demand centres, especially Wellington, are not.
National GDP still expanded 0.2 percent in the June quarter, according to Stats NZ. Construction rose 2.7 percent. Public administration contributed. Yet the recovery is uneven. South Island unemployment sat at 3.7 percent not seasonally adjusted. The North Island rate was 6.0 percent. That split maps almost perfectly onto ASB’s geography.
Why Canterbury has the full package
Mundy told reporters Canterbury has the full package right now. High dairy prices boosted export returns. Continued population growth and major events supported by its new stadium helped activity in the quarter.
ASB cited Canterbury retail sales up 8.8 percent year-on-year — the strongest regional retail print in its pack. Tourism spending in the region was down about 4 percent year-on-year. Locals and farm-linked cashflow, not visitors, did the heavy lifting.
Employment in Canterbury rose 2.6 percent year-on-year on ASB’s read. Unemployment was around 3.6 percent. House prices rose 3.3 percent over the year and were nearly back to their Covid-era peak.
Taranaki’s leap from near the bottom to second was attributed to dairy and meat strength plus Fonterra’s large capital return to farmer shareholders. Southland completed a South Island–primary podium. Bay of Plenty fell from first in Q1 to 11th in Q2, showing how quickly horticulture- and construction-led spikes can fade in relative rankings. Auckland sat mid-table at sixth, still dragged by housing.
The drivers behind Wellington’s rank
Three forces dominate the capital’s scoreboard weakness.
First is fiscal consolidation. Te Kawa Mataaho Public Service Commission data show core Public Service FTEs peaked at 65,699 in December 2023. By 30 June 2025 the figure was 62,654 — a fall of 4.6 percent, or 3,044 FTEs, from peak. The annual drop from June 2024 was 1.4 percent, or 883 FTEs.
Wellington location still held about 42.6 percent of Public Service staff at June 2025, down from 43.6 percent a year earlier and a 2021 high of 44.9 percent. Headcount in the Wellington location was around 26,700. Government policy aims to take core FTEs to no more than 55,000 by July 2029, with projected operating savings on the order of $2.4 billion along the path.
Infometrics principal economist Nick Brunsdon has illustrated that a mid-teens percentage cut applied to Wellington’s core public-service population of just over 27,000 (excluding frontline education and health) could imply roughly 3,700 local job losses if incidence stayed geographic. Even if final incidence is more dispersed, first-round effects hit CBD office demand, contractors, consultants, hospitality and the professional-services cluster that grew around the public balance sheet.
Colliers reported Wellington CBD office vacancy at 12.3 percent in December 2025 — the highest in over a decade on its series. Prime vacancy was 7.5 percent. Secondary was 14.4 percent. Soft demand was linked to the weaker economy and reduced public-sector requirements. CBRE’s figures run higher on a different base; methodology gaps matter and the series should not be averaged silently. Industrial vacancy stayed tight near 2.8 percent on land scarcity — a reminder the region is not uniformly idle.
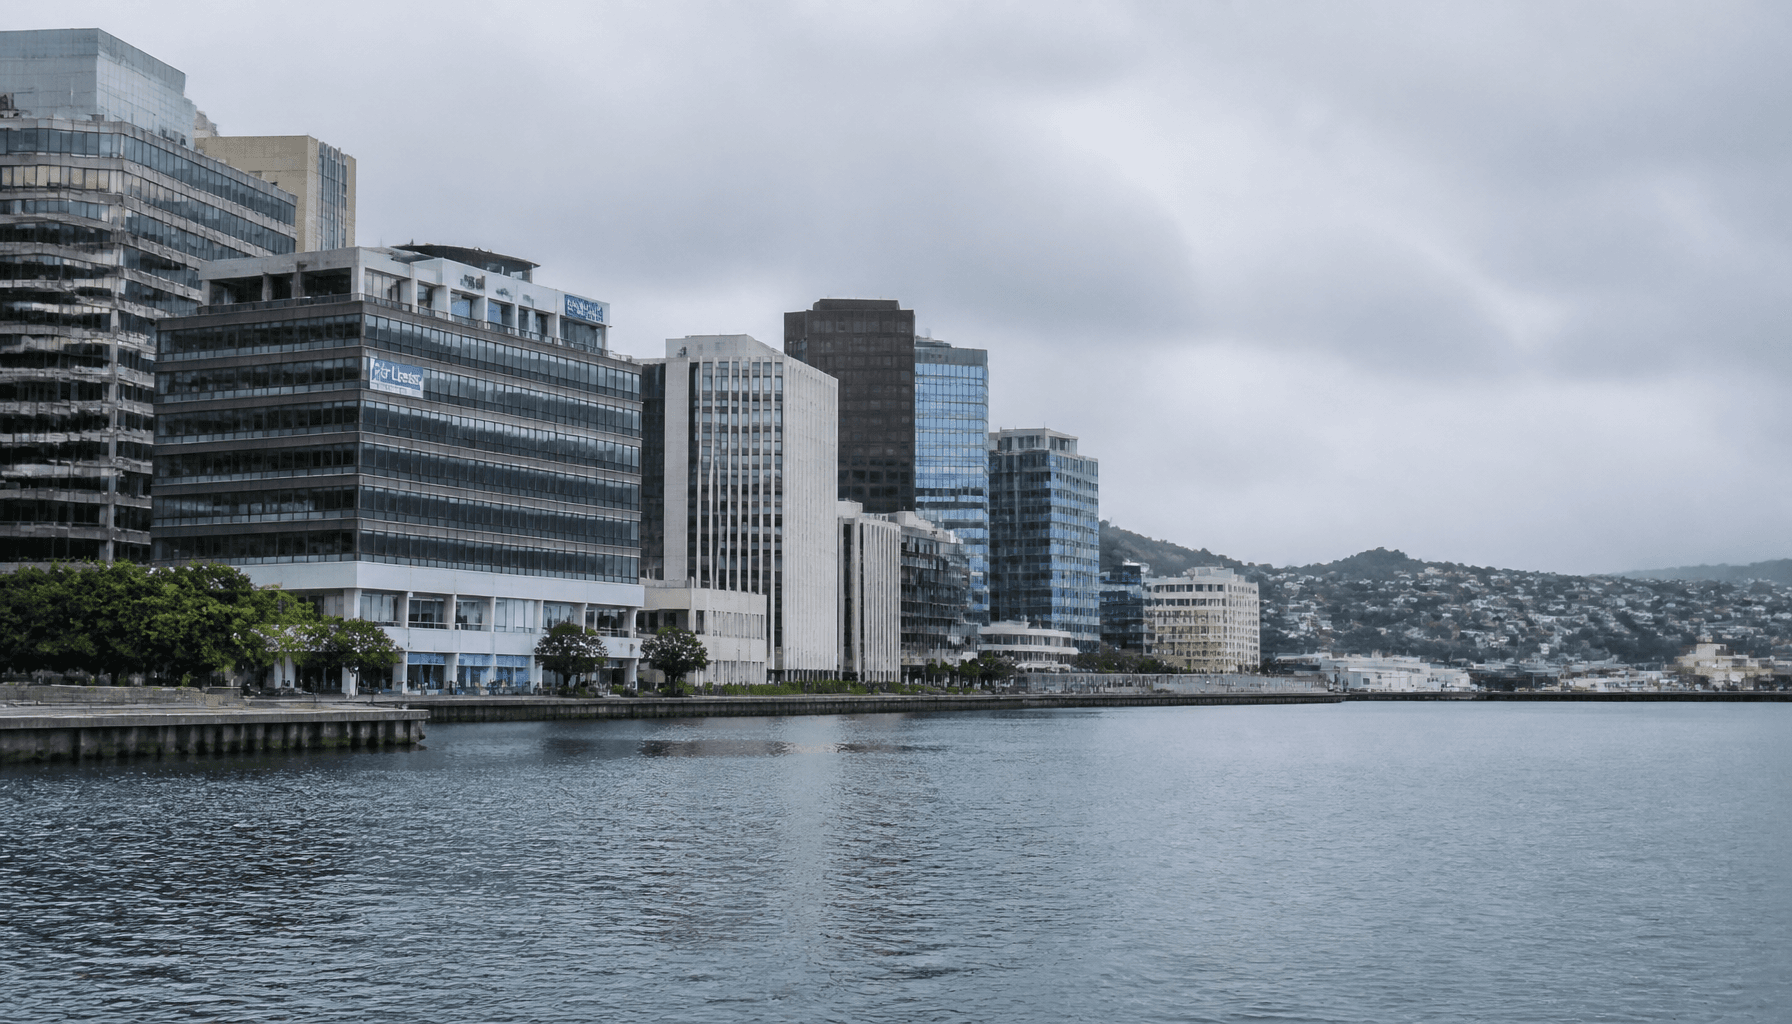
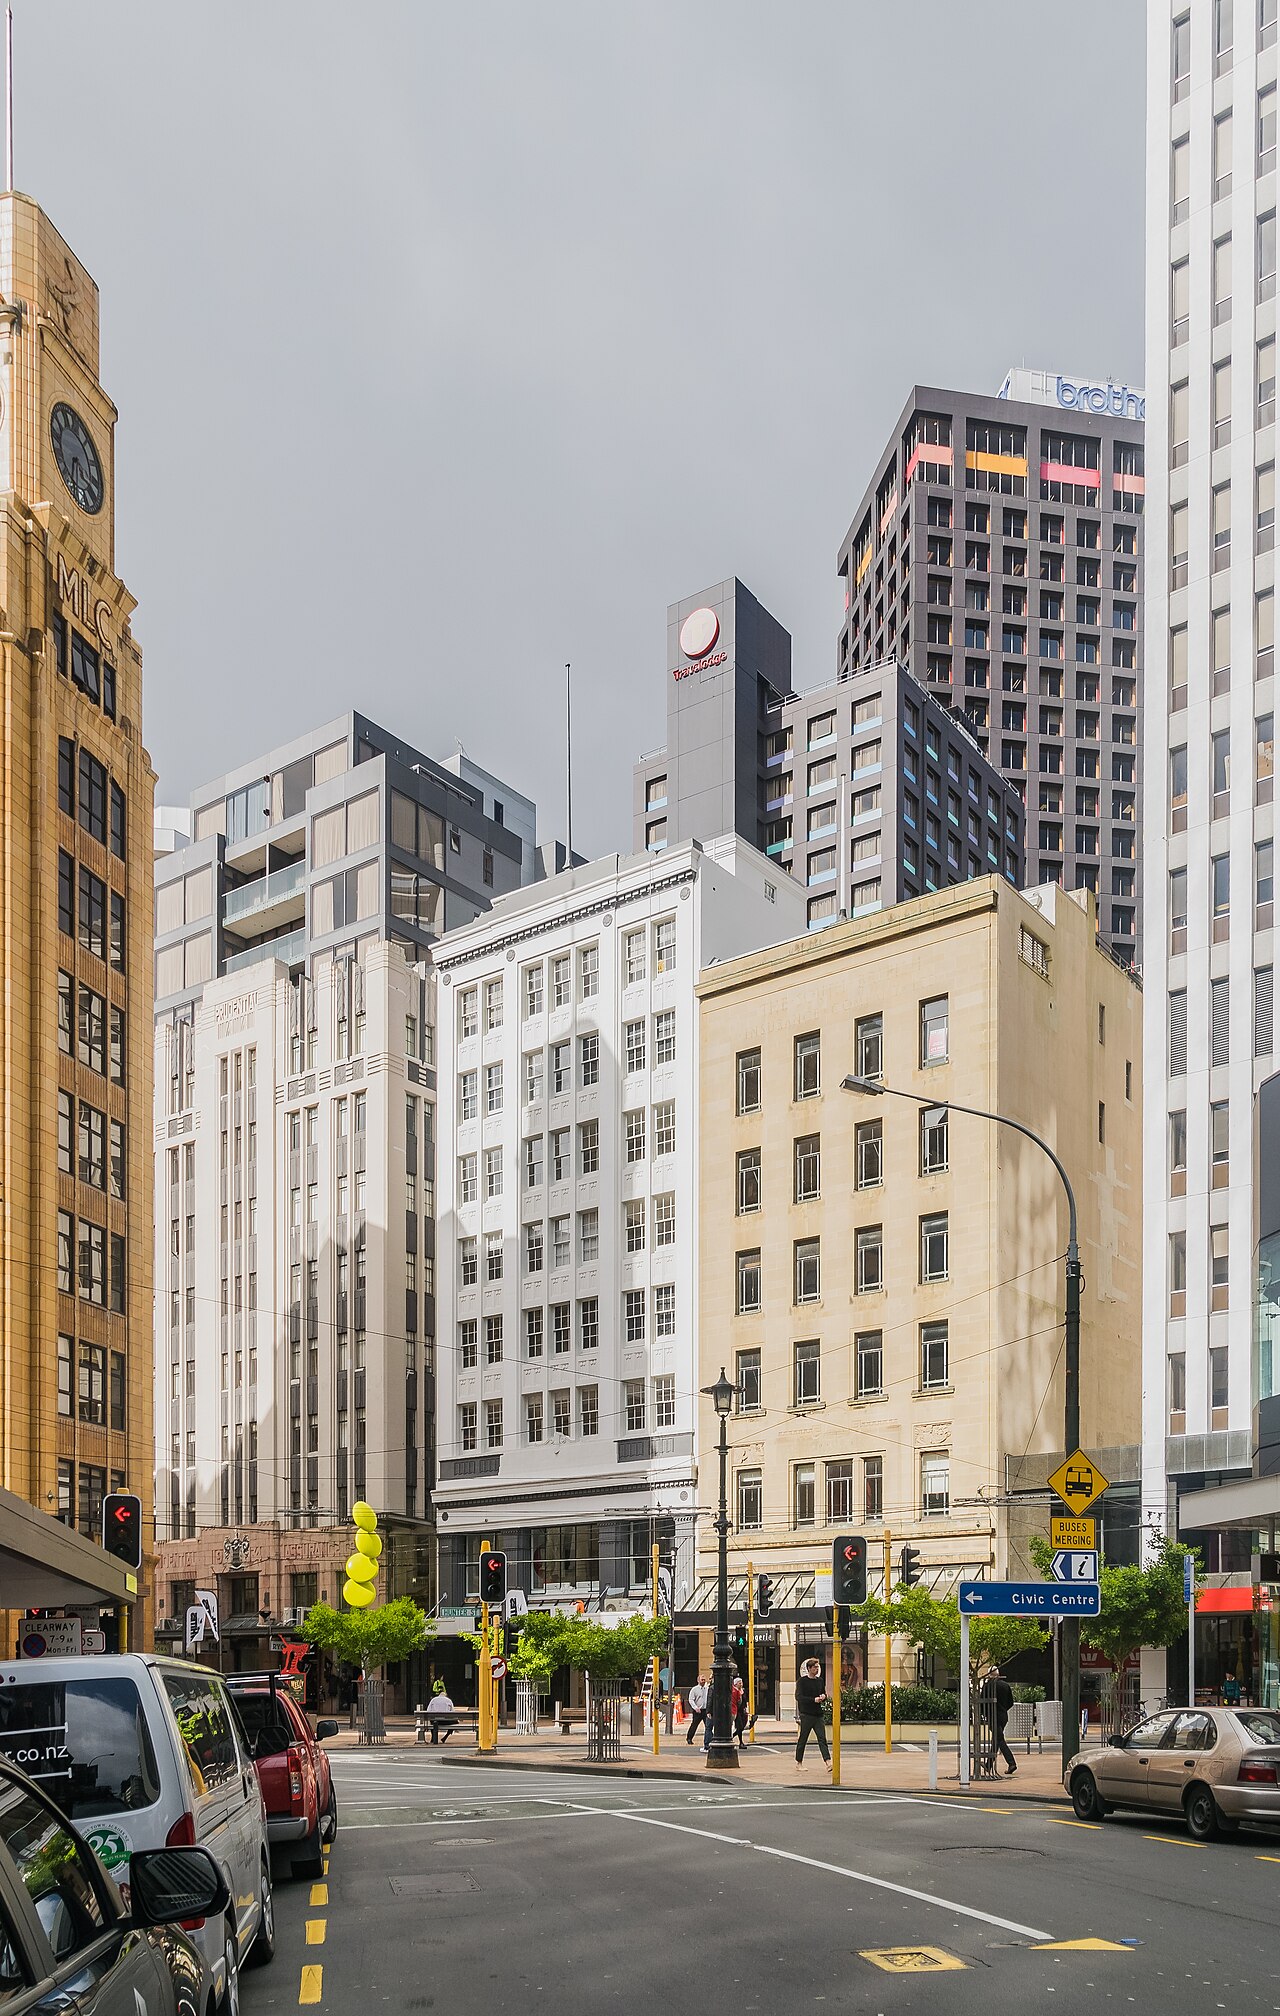
Wellington's Lambton Quay, at the heart of a CBD where Colliers put office vacancy at 12.3 percent in December 2025, the highest in over a decade.
Second is housing and population. Stats NZ subnational estimates put the Wellington region at 543,400 at 30 June 2025 with 0.0 percent annual change. Natural increase offset a net international migration loss of about 1,700, concentrated in Wellington city (about 1,500). Wellington city fell 0.3 percent. Porirua fell 0.4 percent. Upper Hutt fell 0.2 percent.
No population growth means less underlying demand for dwellings, school rolls, retail floorspace and entry-level hiring. ASB and REINZ/Cotality-linked commentary put Wellington roughly 26–30 percent below the October 2021 nominal peak. QV’s late-winter 2026 window showed Wellington city values falling about 3.5 percent over three months — among the weakest large-market moves. Christchurch and Canterbury have been nearer flat-to-up and closer to prior peaks on ASB’s read.
Third is construction drought. Stats NZ building consents for the year ended June 2026 show Wellington region new dwellings at 2,217, up 17 percent on a very weak prior year. Canterbury consented 8,647, up 33 percent. Per 1,000 residents, Canterbury’s intensity is roughly three times Wellington’s. Infometrics has flagged non-residential consents in Wellington City sharply lower year-on-year — a second collapse on top of residential. Trades, merchants and consultants that ride the consent cycle are running cold in the capital while Canterbury still has a pipeline.
Dairy cash and the rural podium
Fonterra completed the sale of its Mainland Group consumer businesses to Lactalis and returned about $3.2 billion tax-free capital (roughly $2 per share) to farmer shareholders around 14 April 2026. Dividends lifted the April cash event toward about $3.9 billion. Fonterra’s own disclosures and USDA FAS reporting support the order of magnitude.
ASB earlier estimated eventual spend diffusion around $4.5 billion nationally — about 1 percent of nominal GDP. First-round recipients are farmer shareholders concentrated in Waikato, Canterbury, Taranaki, Southland and lower North Island dairy belts — not Wellington.
Farmgate milk price for 2025/26 held a high midpoint near $9.70/kgMS after a record $10.16 in 2024/25. The 2026/27 season opened softer after GDT weakness, though some agri banks have argued a path back toward $10 if supply tightens. That cashflow supports rural retail, vehicle sales, farm services and regional housing in exactly the ASB top-three regions.
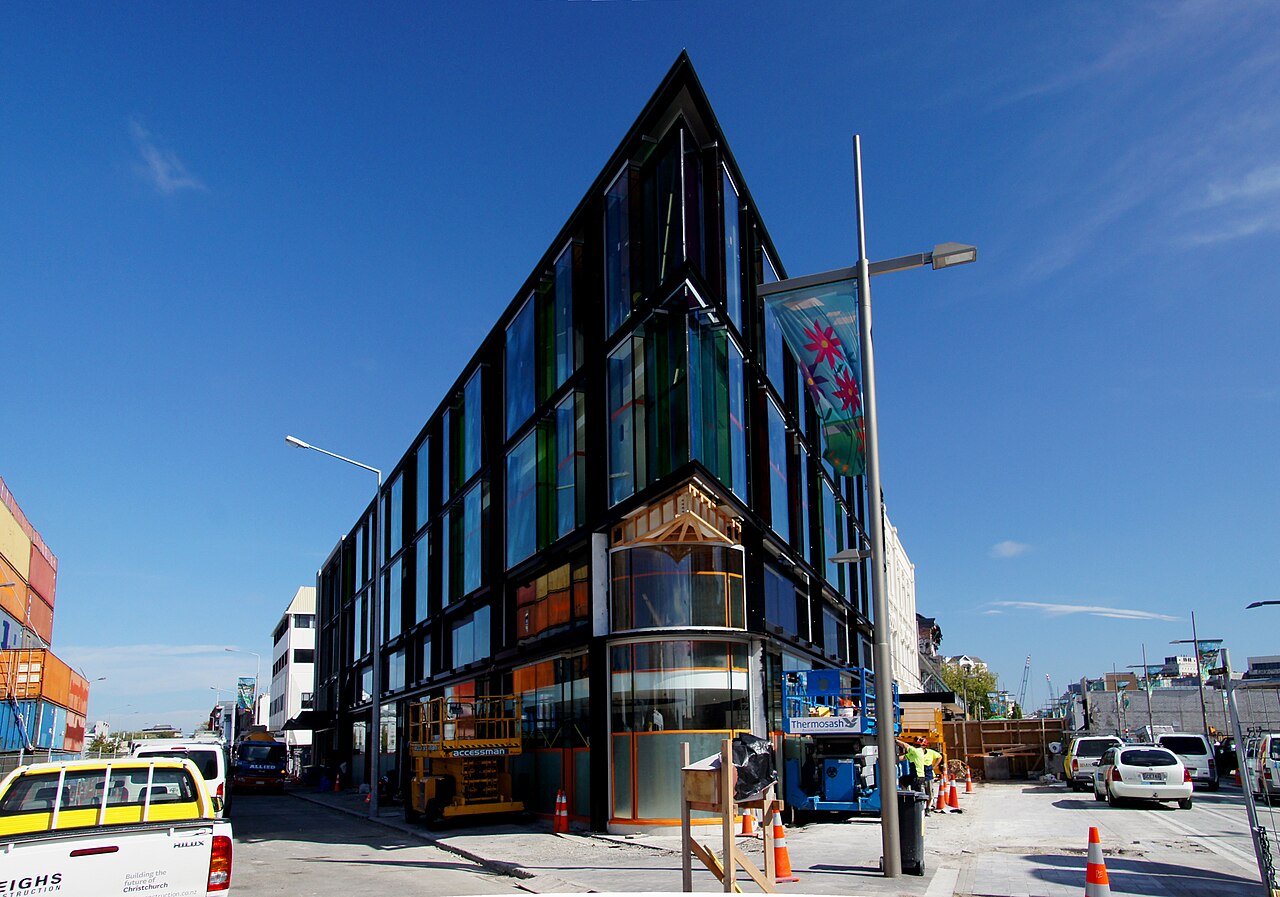
Canterbury's post-quake rebuild left a lasting construction and population base that Wellington never had an equivalent private demand shock to build.
Monetary policy as a national blunt instrument
On 2 September 2026 the Reserve Bank raised the OCR 25 basis points to 2.75 percent. June quarter CPI inflation was 4.1 percent year-on-year, with a large fuel component tied to Middle East conflict risk. The remit remains a 1–3 percent target band with a 2 percent midpoint. Mundy’s interview reference to a 1–4 percent target should be read as a slip; the formal remit is 1–3 percent.
The September MPS central path lifts the OCR gradually toward the low-3s over about two years, with inflation returning to band through 2027 if second-round effects are contained. For Wellington this matters because the OCR does not ease just because the capital is in a localised demand hole. Higher-for-longer mortgage and term deposit rates prolong the housing correction and keep debt-service pressure on mortgaged households precisely where prices and confidence are weakest.
Inflation is something that everyone is feeling across the board, irrespective of how the economy is evolving in those regions.
Mundy has made the operational point that inflation is felt everywhere even when real activity is two-speed. That is the justification the Reserve Bank will keep using. National policy rates cannot micro-target a capital-services slump without overheating export regions still running hot on commodities — a pattern familiar across G7 central banks.
Where the trade-offs bite
Fiscal consolidation toward 55,000 FTEs and contractor restraint cuts operating spend. It may help the national inflation and debt path. It also concentrates first-round income, CBD office and hospitality losses in Wellington, where more than two-fifths of core public service staff sit.
The OCR anchors inflation expectations and cools hot export regions. It also prolongs mortgage service pressure and housing turnover drought exactly where prices are weakest.
Wellington City Council cut its 2026/27 average rates rise to 5.9 percent, including the sludge levy — the lowest in six years — after identifying tens of millions in savings versus the long-term plan path. Mayor Andrew Little fronted the pivot. Greater Wellington regional rates remain firmer. Water charges moved to Tiaki Wai from 1 July 2026. Infometrics-style affordability work still places combined rates and water high relative to household income in the capital.
Office-to-residential conversion can cut secondary vacancy and add housing supply only if interest rates, seismic operating costs and sale prices clear developer hurdles. Those are 2027–29 variables.
Dairy capital returns and high milk prices lift national exports, the New Zealand dollar and fiscal receipts that fund capital-hosted services. They also widen ASB regional ranks against Wellington. That is a political irony, not a policy error in the farmgate cheque itself.
Second-order effects households and firms should watch
Public FTE and contractor cuts reduce direct income in Wellington postcodes. Cafe, retail and services takings in the CBD and inner suburbs follow. Hybrid work plus lower headcount reduces office absorption. Secondary vacancy rises. Rents soften. Capex is deferred. Commercial valuations and local authority rating bases weaken over time.
House price falls produce negative equity and wealth effects. Renovations and durables are deferred. Building consents and merchant sales stay weak. Near-zero population growth means fewer household formations and less dwelling demand.
A national OCR at 2.75 percent on a rising path keeps mortgage serviceability gates tight. Housing turnover stays low. Real-estate agency, legal and moving-services income stays soft. Banks mark Wellington collateral still well below peak.
Net migration loss from the city can soften national potential output if working-age leavers exit New Zealand rather than relocate domestically. Stats NZ’s 2025 subnational estimates already show the migration hole. Retail Trade Survey regional splits will keep showing a geographic wedge that complicates a single national consumption narrative for the Reserve Bank and Treasury.
Historical context
Wellington has underperformed on ASB’s scoreboard for multiple quarters. It finished last in Q4 2025. It improved only into the teens in Q1 2026 when Bay of Plenty briefly topped on kiwifruit and construction. It returned to joint last in Q2 2026. Persistence matters. This is not one bad print.
The post-2023 fiscal consolidation followed a long public-employment expansion. It layered on the national monetary tightening cycle, a migration pause and a housing correction that hit high-price, high-leverage markets hardest. The result is a capital-specific downturn inside a national soft landing and uneven recovery.
Christchurch’s post-quake rebuild decade left Canterbury a lasting construction and population base. Wellington never had an equivalent private demand shock absorber.
Australia’s CommBank State of the States routinely shows resource and population-growth states outperforming. The ACT’s rank wobbles with federal public-service hiring and efficiency dividends — the closest large-economy analogue to Wellington. When APS headcount stalls, Canberra retail, cafes and mid-tier office feel it first despite high average incomes.
The counter-argument
The strongest opposing read deserves a fair hearing. Mundy himself has said aggregate Wellington jobs have not been as weak as street-level mood suggests. The malaise is housing, population and construction as much as pink slips.
Colliers’ split shows premium CBD office still relatively full even as secondary vacancy rises — a barbell, not a ghost town. Industrial vacancy is low. Parts of the region still have land-constrained strength.
Wellington City Council’s 5.9 percent rates rise and savings programme is a genuine local fiscal pivot that may stabilise household cashflow relative to the long-term plan path.
National GDP and construction are expanding again. If OCR-sensitive housing demand turns by 2027 along ASB’s mild national recovery path — roughly flat in 2026, then mid-single-digit later — Wellington’s deep discount to peak could attract yield buyers and first-home buyers earlier than mood suggests. Conversions and seismic operating costs remain brakes.
Gisborne shares last place for different reasons: scale, primary volatility and weather. Equating the capital with Gisborne on rank alone overstates structural identity.
Scoreboard last place is not proof the city is finished. It is proof relative momentum is weak on the indicators ASB tracks.
Open questions
Will the core public service path to 55,000 FTEs by 2029 keep geographic incidence on Wellington, or disperse? Verified contractor and consultant spend trajectories beyond secondary reporting remain incomplete on primary Public Service Commission tables.
Does Wellington housing stabilise after the roughly 3.5 percent three-month QV print, or extend through 2027 as OCR-sensitive turnover stays thin?
What is Fonterra’s 2026/27 final milk price outcome relative to the softer opening midpoint? That will decide how many more ASB podiums Canterbury, Taranaki and Southland collect.
Can private knowledge-sector growth, tertiary recovery and infrastructure replace a permanently smaller public footprint before secondary vacancy and rating-base effects entrench?
When does CBD office vacancy peak on Colliers and CBRE bases, and do conversions clear stock at prices that work for developers?
How much weight does ASB’s composite place on housing and population versus jobs? The detailed Q2 PDF indicator weights were not independently retrieved in verification; rankings rest on ASB commentary via secondary reporting.
What to watch next
Stats NZ retail and employment indicators for the September and December 2026 quarters will test whether the Canterbury–Wellington split persisted. REINZ days-to-sell and QV monthly values will show whether late-winter price falls stabilise. The Reserve Bank’s next OCR decisions will reprice fixed mortgages into the listing season. Fonterra’s milk price path will set the rural cashflow backdrop into Christmas and beyond.
Over two to three years the strategic question is whether private professional services, tech, creative industries and tertiary education can replace a smaller public footprint. Without that, Wellington risks lower steady-state CBD occupancy, permanently higher secondary vacancy and continued scoreboard underperformance even if absolute living standards remain high. Fiscal discipline after a long expansion of the public payroll was a national choice with a concentrated local price. The capital’s next chapter depends on private demand filling the gap the scoreboard already measures.